Your bank in
Will it simply be digital, or fundamentally different?
Six decisions that will define the next generation of banking.
The next transformation of banking has already begun.
For the last decade, banks have focused heavily on becoming digital. The next decade will demand something more fundamental.
Customers will expect banking to be immediate, intelligent and almost invisible. Artificial intelligence will increasingly support decisions. Payments will become more connected. Financial services will move beyond traditional channels. Regulators will expect greater transparency, resilience and accountability.
At the same time, banks must protect the trust on which the industry is built.
The challenge facing leadership is therefore not simply:
"What technology should we implement?"
It is:
"What kind of bank do we want to become?"
The six decisions in this booklet are intended to start that conversation.
If you were building your institution today, would you build it the same way?
Synthesizing technological ambition with institutional governance defines modern financial stewardship.
The next four years may reshape banking more than the previous ten.
The forces transforming financial services are beginning to converge.
- Today
Digital channels have become expected. Customers increasingly demand simplicity, speed and continuous access.
- Next
Artificial intelligence moves from experimentation into everyday banking operations.
- Then
APIs, embedded finance and connected ecosystems increasingly blur the boundaries between banks, fintechs, businesses and platforms.
- By 2030
Leading institutions may operate less like traditional banks and more like intelligent financial ecosystems — connected, data-driven, highly automated and increasingly personalised.
If the pace of change accelerates, is your bank designed to adapt — or will its technology become the constraint?
The challenge is not predicting every technology that will emerge. The challenge is building an institution capable of adapting when it does.
Build around the customer, not the channel
Customers do not think in terms of core banking, mobile banking, branches, APIs or payment platforms. They simply expect banking to work.
The future customer experience will increasingly connect every interaction — mobile, web, branch, agent, contact center and third-party ecosystem — into one continuous relationship.
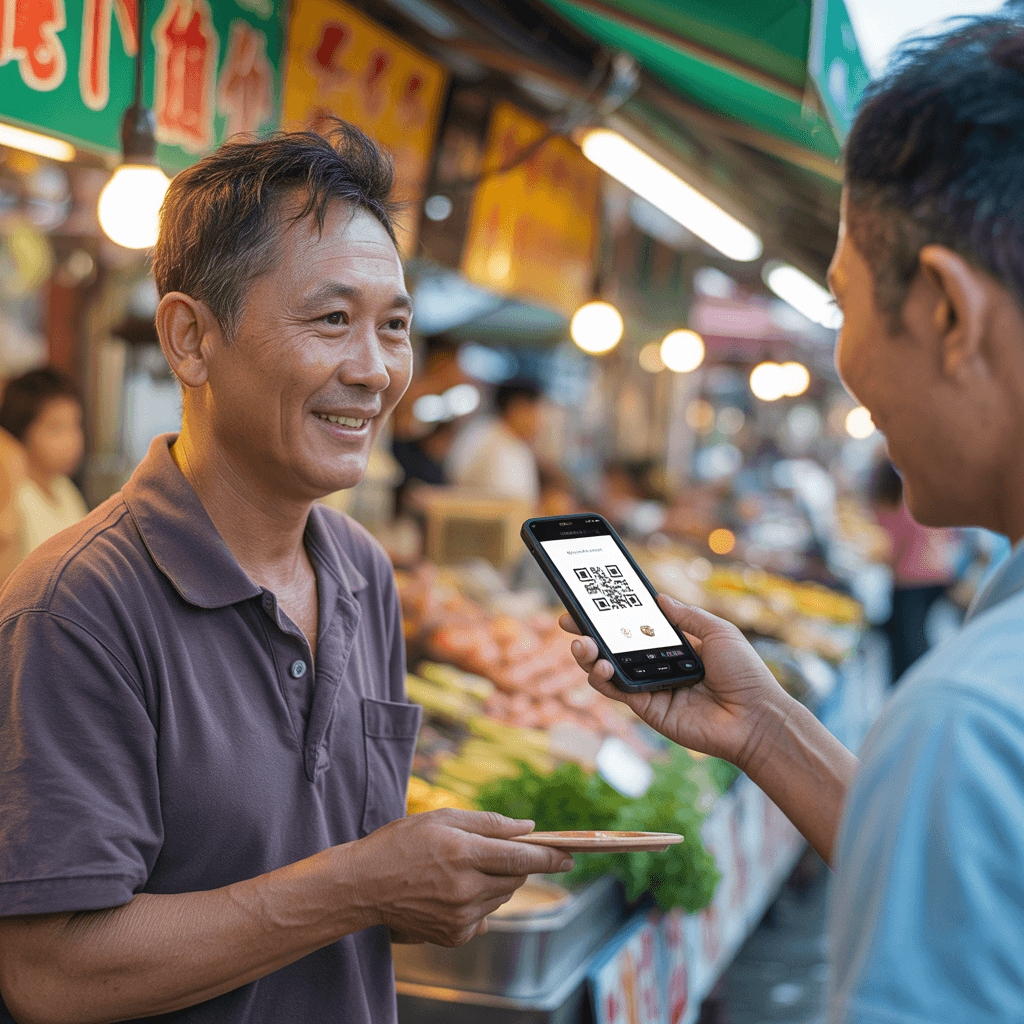
For banks serving developing and emerging markets, this also creates an important opportunity. Technology can extend banking beyond traditional branch networks, enabling greater accessibility, financial inclusion and cost-effective service delivery.
In 2006, DFCC Bank introduced M-Teller at the Dambulla Economic Centre, bringing banking services directly to busy businesspeople who found it difficult to leave their businesses to visit a bank branch.
- Understand the customer across every channel
- Personalise services using data and intelligence
- Remove friction from onboarding and servicing
- Extend banking beyond the branch
- Serve customers wherever economic activity happens
Are your digital channels connected around the customer — or simply connected to the core?
Modernise the core without losing control
Every digital ambition eventually reaches the core.
A modern bank must be able to introduce new products quickly, integrate new channels, connect external ecosystems and respond to regulatory change without creating greater complexity. This is why the conversation around core banking is changing. The question is no longer simply whether a core system can process transactions. The question is whether the architecture can support continuous innovation.
Modernisation does not always require a disruptive "big bang" replacement. Banks can increasingly modernise progressively — introducing new capabilities while protecting operational continuity. By decoupling core layers and building microservices, institutions reduce risk while gaining the agility needed to compete in a rapidly evolving connected landscape.
With the support of the open API architecture of the ABANX platform, Pan Oceanic Bank Solomon Islands became the first bank in the Solomon Islands to implement an ATS, leveraging the open API capabilities and seamless integration offered by ABANX.
- Modular architecture
- API-first connectivity
- Cloud-native infrastructure
- Highly configurable
- Robust enterprise security
- Elastic scalability
Is your core banking platform enabling innovation — or determining how quickly you are allowed to innovate?
Make artificial intelligence operational
Artificial intelligence will not transform banking because banks have chatbots. Its real impact will come when intelligence becomes embedded throughout the institution.
AI can increasingly support decisions across areas such as risk modeling, core operations, regulatory compliance, and customer lifecycle management.
By systematically operationalizing intelligence, leading financial institutions shift AI from isolated digital experiments into a core engine of sustainable competitive advantage.
Do not begin with AI. Begin with the business problem.
Establishing an industrial-grade AI command center allows operational risk officers to oversee model deployment, tracking continuous improvement and real-time performance.
The opportunity is significant. But so is the responsibility.
As intelligence moves from experimentation into production, banks must build governance, explainability and continuous oversight into every layer of the operating model.
Regulators globally are increasing scrutiny on algorithmic models. Financial institutions must demonstrate clear auditability, unbiased training data, and continuous system monitoring.
Without these safeguards, automated systems risk executing faulty processes at scale, harming both customers and institutional trust.
The strongest institutions will not simply have an AI strategy. They will develop an AI operating model.
Where could artificial intelligence remove the most friction from your institution today?
From experimentation to integration — intelligence must be governed, embedded and continuously improved.
Prepare for the next payment revolution
Payments are becoming faster, more connected and increasingly invisible. Customers and businesses now expect money to move with the same simplicity as information.
The modern landscape is rapidly shifting toward instant settlement ecosystems, ubiquitous digital wallets, and seamless cross-border payment platforms. Embedded payments are fundamentally transforming user experiences, integrating financial services directly into consumer and business applications. Interoperability has ceased to be a technical feature; it is now a core expectation of global trade and domestic commerce.
These shifts are steadily changing customer expectations and competitive boundaries.
Are your payment systems designed to move money — or to build relationships, generate insights, and create new opportunities?
The strategic question is therefore not simply: how do we process payments?
It is: how do payments strengthen our customer ecosystem?
Cross-border transactions and global remittances have transformed from high-cost back-office processes into primary relationship anchors. For economies integrated with international labour markets, trade networks, and global diaspora communities, the payment rail represents the most vital point of contact. By optimizing real-time settlement channels and reducing frictional drag, progressive institutions are securing secondary value flows — converting high-frequency transactional data into predictive advisory capabilities and tailored credit solutions.
Payments do more than move money.
For financial institutions, the next generation of payments creates opportunities far beyond transaction processing.
Every payment is a touchpoint, helping banks understand, engage and serve customers more effectively.
Payment activity provides real-time insights into customer behaviour, needs and opportunities.
These insights can unlock additional financial services, from lending and savings to insurance and investment solutions.
Payments are no longer just transactions. They are a strategic gateway to deeper relationships, richer insights and broader growth opportunities.
Payments are not the end of the journey. They are the beginning of what’s next.
Payments today. Greater possibilities tomorrow.
Digitise governance, not just banking
Many banks have transformed customer-facing processes while critical management processes remain surprisingly manual.
These processes sit at the heart of institutional governance. Yet information can still be fragmented across email, paper, spreadsheets and disconnected systems.
From meetings and approvals to institutional intelligence.
The future bank will increasingly treat governance as a digital capability. Digitised governance can create greater transparency, stronger accountability, faster decision making and a clearer institutional audit trail.
Technology should not replace governance. It should make good governance easier to practice.
Can your leadership team see what has been decided, who approved it, what remains outstanding and what requires attention in real time?
Turn ESG from reporting into management intelligence
Environmental, Social and Governance considerations are increasingly becoming part of how institutions understand long-term risk, responsibility and value creation.
Yet many organizations still approach ESG primarily as a reporting exercise.
The greater opportunity is to turn ESG information into management intelligence.
The objective should not simply be to create another report.
It should be to help management understand where the organization stands and where intervention may be required.
Measure. Understand. Act.
Can your board view ESG performance with the same clarity that it views financial performance?
The future bank will not be defined by a single technology.
It will be defined by how effectively its technologies work together.
- Customer experienceMobileWebBranchAgentEmbedded banking
- IntelligenceAIAnalyticsPersonalisationDecision support
- Financial capabilitiesDepositsLendingPaymentsInvestmentsRemittancesTrade
- Digital coreAccountsCustomersProductsTransactionsWorkflow
- ConnectivityAPIsOpen ecosystemsPartnersFintechsExternal platforms
- Institutional controlGovernanceRiskComplianceESGCybersecurityAudit
- Technology foundationCloudDataInfrastructureSecurityResilience
The competitive advantage will increasingly come not from owning more technology but from connecting it better.
How ready is your institution?
Digital transformation has no single finish line. But leadership should understand where the organisation stands. Rate your institution across these eight dimensions.
Can customers move seamlessly across channels?
How quickly can new products and services be introduced?
How easily can your bank connect with external platforms?
Is data actively supporting decisions?
Can your payment infrastructure support emerging customer expectations?
Are leadership decisions and approvals digitally managed?
Can management measure ESG performance effectively?
Can your architecture scale securely as the organisation grows?
0%
This is a quick self-check, not a benchmark — the conversation it starts is what matters.
Transformation does not need to happen all at once.
The most successful technology journeys are rarely defined by the number of systems implemented. They are defined by priorities.
Technology must serve the strategy of the institution — not become the strategy itself.
Successful transformation is not one large leap. It is a disciplined sequence of assessing, prioritising, modernising, connecting, scaling and optimising.
Technology is only valuable when it solves a real banking problem.
As a financial technology company with the banking heritage of DFCC Bank, our approach combines financial-sector understanding with software engineering and implementation capability.
One partner. Multiple capabilities.
Strategy translated into practical technology.
Modern banking platforms designed for agility, inclusion and growth.
Technology supporting domestic and cross-border financial ecosystems.
Solutions supporting margin trading and investment-related operations.
Board, committee, approval and institutional workflow automation.
Management dashboards designed to turn ESG information into actionable insight.
Bespoke software, systems integration, technology operations and financial-sector consulting.
2030 starts with the decisions you make today.
Imagine the institution you want to become.
Then onboard the technology that makes it possible.